


Obligaciones del empleador sobre medidas de protección de la familia
Introducción
La Ley de Protección Integral a la Familia (ley 1361 de 2009) fue adicionada y complementada mediante la Ley 1857 de 2017, la cual, entre otros asuntos, en su artículo 3 estableció unas obligaciones del empleador respecto de sus trabajadores con el fin de permitirles cumplir con sus deberes familiares.
Con base en lo anterior, la ley 1857 de 2017, estableció dos obligaciones en cabeza del empleador, la primera, consistente en la posibilidad de que el empleador y el trabajador acuerden jornadas de trabajo flexible que permitan a éste último poder cumplir con sus deberes de acompañamiento y protección a los miembros de su grupo familiar, y la segunda, referida a la obligación imperativa del empleador de dar una jornada familiar semestral a sus trabajadores para que compartan con sus familias.
Dicha ley ha generado varias inquietudes en cuanto su alcance y forma de implementación, motivo por el cual el 24 de septiembre de 2019 el Ministerio de Trabajo emitió un concepto unificado en donde respondió los asuntos que le consultan más frecuentemente en relación con este asunto. A continuación nos referimos a dicho concepto del Ministerio.
Facultad de acordar jornadas de trabajo flexible con los empleados
De acuerdo con el artículo 161 del Código Sustantivo del Trabajo, la duración máxima de la jornada ordinaria de trabajo en Colombia es de ocho (8) horas por día y cuarenta y ocho (48) horas a la semana, lo anterior teniendo en cuenta que en Colombia es usual que los empleados trabajen de lunes a sábado. Sin embargo, la ley 1857 de 2017 establece la posibilidad de que el empleador pueda “adecuar los horarios laborales para facilitar el acercamiento del trabajador con los miembros de su familia”.
En este sentido, es posible que el empleador y el trabajador acuerden un horario flexible y unas condiciones de trabajo para facilitar el cumplimiento de los deberes familiares del trabajador. El Ministerio de Trabajo al referirse a este asunto expresó que la flexibilización de la jornada laboral debe estar incluida en el Reglamento Interno de Trabajo del empleador. Es de aclarar que esta primera “obligación” no es una obligación propiamente dicha, sino una facultad que tiene el empleador respecto de sus trabajadores.
Uno de los interrogantes más frecuentes en relación con esta las obligaciones de protección integral a la familia es ¿quiénes son las personas incluidas en el grupo familiar respecto del cual el trabajador tiene deberes de acompañamiento y protección?, pues la Ley 1857 se limita a indicar estas obligaciones aplican para permitir al trabajador cumplir con sus obligaciones familiares de protección y acompañamiento frente a su cónyuge, compañero/a permanente, o parientes dentro del tercer grado de consanguinidad con ocasión de su edad o situación de discapacidad.
En este sentido, el Ministerio hizo referencia a las definiciones legales de mayoría de edad y vejez y a la definición jurisprudencial de “persona en condición de discapacidad”, de tal suerte que se entiende que el deber de acompañamiento y protección en razón a la edad obedece a los familiares menores de edad, es decir, que tienen menos de 18 años de edad o adultos mayores, es decir, aquellas personas que tienen más de 60 años de edad.
En relación con las personas en situación de discapacidad, el Ministerio hizo referencia a la definición de la Corte Constitucional mediante sentencia C-147 de 2017 en donde se indicó que la situación de discapacidad son las condiciones ambientales, físicas, biológicas, culturales y sociales que pueden afectar la autonomía u participación de una persona con su núcleo familiar, la comunidad y la población en general.
Condiciones de otorgamiento de la Jornada Laboral Semestral
Ahora bien, en relación con la obligación del empleador de disponer de una jornada laboral cada semestre para permitir al trabajador un espacio para compartir con su familia, esta puede cumplirse de 3 maneras, cualquiera de ellas asumida por el empleador con su propio peculio:
- El empleador dispone a su criterio el sitio y forma en que se realizará la jornada.
- De manera coordinada con la Caja de Compensación Familiar a la que se encuentre afiliado el trabajador.
- Cuando no se pueda dar ninguna de las dos opciones anteriores, el empleador puede conceder al trabajador una jornada libre remunerada para cumplir con los fines de la Ley 1857 de 2017.
En caso de que el empleador elija la última opción, no podrá inmiscuirse en la forma que el trabajador decida pasar su jornada laboral en familia, lo anterior en virtud del derecho constitucional establecido en el artículo 15 de la constitución política a la intimidad personal y familiar. Tampoco podrá el empleador solicitar al trabajador “prueba” de la realización de la jornada familiar, pues esto atenta contra el principio de presunción de buena fe en la actuación de las partes previsto en el artículo 55 del Código Sustantivo del Trabajo.
Participantes en la Jornada Familiar
Debido a que la ley no definió los miembros de la familia que participan en la jornada familiar, el Ministerio acudió a la definición de familia adoptada por la Corte Constitucional mediante sentencia T-281 de 2018, en donde se entiende por familia “una institución sociológica que tiene como fines esenciales entre otros la ayuda mutua y el sostenimiento de sus miembros.”.
El Ministerio entonces señaló que corresponde al empleador utilizar los criterios de razonabilidad y proporcionalidad para establecer quiénes participarán en la jornada familiar semestral, teniendo en cuenta que es él quien debe soportar la carga económica de la jornada familiar en cualquiera de las modalidades que decida llevarla a cabo.
Lo anterior no implica que el empleador no pueda, a su libre arbitrio, permitir que participen en la jornada familiar personas diferentes al núcleo familiar del trabajador, sin que ello se convierta en una obligación del empleador.
Cumplimiento de la jornada familiar frente a trabajadores con novedades
En primer lugar, el cumplimiento de la obligación de implementar una jornada familiar semestral es independiente de la fecha de inicio o terminación del contrato de trabajo. De esta manera, el empleador es libre de definir cuándo y cómo va a llevar a cabo la jornada en cada semestre del año, por lo que si se programó en un día específico y se llevó a cabo, no está obligado a programar una nueva jornada para los empleados que en esa fecha estaban incapacitados, en licencia o vacaciones, en este sentido, quienes no participaron en esta jornada por alguna de estas novedades, la disfrutará en el día que el empleador disponga para el semestre siguiente, pues el empleador sólo tiene la obligación de programar una sola jornada en cada semestre.
Consecuencias del incumplimiento de la obligación
El incumplimiento de la obligación de disponer, como mínimo, de una jornada familiar por semestre, puede conllevar a la imposición de multas al empleador por parte del Ministerio de Trabajo, las cuales pueden estar entre 1 salario mínimo legal mensual vigente (SMLMV) y 5.000 SMLMV, dependiendo de la gravedad de la infracción, es decir, entre COP 828.116 y COP 4.140.580.000.
Acumulación de jornadas familiares no otorgadas
La ley no previó la posibilidad de acumular jornadas familiares no disfrutadas por el Trabajador; sin embargo, es la opinión del Ministerio que, en caso de que esta entidad inicie un proceso de inspección por transgresión de la norma, el haber concedido la jornada familiar aún por fuera del periodo establecido en la norma, puede ser considerado como un atenuante o eximente de responsabilidad del empleador.
Complementación del horario de trabajo cuando la jornada ha sido concedida
Por su parte, el empleador cuenta con la facultad de acordar un horario laboral complementario para compensar la jornada laboral semestral otorgada al empleado para compartir con su familia, lo anterior por cuanto, el empleador ha remunerado un servicio sin que éste haya sido prestado. Pues bien, el Ministerio aclaró que las horas de complementación que superen la jornada máxima legal de un día cualquiera deben ser compensadas con los recargos que la ley señale para el trabajo suplementario o de horas extra, ya sean diurnas, nocturnas o dominicales.
De cualquier manera, debe tenerse en cuenta que el empleador puede decidir libremente si exige a sus trabajadores la complementación del horario laboral con ocasión del disfrute de la jornada familiar, debido a las cargas que representa para el empleador el reconocimiento del trabajo suplementario de los trabajadores que deban cumplir con un horario laboral complementario.
Otras actividades del empleador no exime el cumplimiento de la obligación de concesión de jornada familiar
Los beneficios extralegales que el empleador quiera dar a sus empleados por mera liberalidad o como fruto de negociaciones colectivas, como tardes libres por cumpleaños, licencia remunerada por matrimonio, celebración de festividades, entre otras, no eximen al empleador de su obligación de otorgar a sus empleados la jornada familiar semestral, pues los primeros son producto de la generosidad y voluntad del empleador o de una negociación colectiva, mientras que la segunda es una obligación de naturaleza legal que tiene una finalidad específica que es garantizar el desarrollo integral de la familia como núcleo esencial de la sociedad.
Disposición de varias jornadas familiares durante el semestre
Pese a que la ley no lo previó, el Ministerio de Trabajo indicó que es posible que el empleador disponga varias jornadas laborales durante el semestre para cumplir con su obligación de disponer de una jornada familiar por semestre, con el fin de permitir que todos sus trabajadores la puedan disfrutar. En efecto, el Ministerio incluso manifiesta que no sólo es posible sino que también es necesario que el empleador organice a sus trabajadores por grupos que puedan en distintas fechas acceder a la jornada familiar, lo cual depende enteramente del empleador y de los lineamientos que defina al respecto en ejercicio de su derecho a la libertad de empresa.
La jornada familiar no se puede realizar en días de descanso del trabajador
El Ministerio manifestó que está prohibido realizar la jornada familiar en los días de descanso del trabajador, pues esta debe hacerse dentro de la jornada laboral, de tal manera que si el reglamento interno de trabajo del empleador prevé el día sábado como un día de descanso remunerado, no puede programar la jornada familiar el día sábado.
Sin embargo, es posible que se programe la jornada familiar el día sábado en los casos en que, siendo el sábado un día laborable, el empleador acuerde con el trabajador una ampliación de la jornada laboral diaria para que el trabajador descanse el día sábado en los términos del artículo 164 del código Sustantivo del Trabajo.
La ley 1857 no requiere reglamentación para su aplicación obligatoria
El Ministerio manifestó que si bien es cierto que la Ley 1857 puede requerir reglamentación en alguno de sus aspectos, esto no implica que su aplicación esté condicionada a que exista una reglamentación, por lo que las obligaciones ahí contenidas deben ser aplicadas sin necesidad de que exista un decreto que las desarrolle.
Conclusión
La aplicación de las normas relativas a la coordinación de horarios flexibles y la disposición de jornadas familiares semestrales constituyen mecanismos de apoyo y fortalecimiento a la familia en desarrollo de lo establecido en la ley 1361 de 2009 y los principios constitucionales de protección a la familia como núcleo de la sociedad.
El concepto unificado del Ministerio de Trabajo aclara varios vacíos legales e interpretativos relativos a las obligaciones del empleador sobre las medidas de protección a la familia, así pues, en esencia, estas “obligaciones” se dividen en dos, una que es la facultad de acordar horarios de trabajo flexibles con los trabajadores para permitirles atender a sus deberes de acompañamiento y protección de su familia y, la segunda, la obligación de disponer de una jornada familiar por semestre para que los trabajadores tengan un espacio para disfrutar con su familia.
La posibilidad de acordar horarios flexibles de trabajo está dirigida a permitir al trabajador del tiempo para poder acompañar y proteger al cónyuge, compañero o compañera permanente o parientes dentro del tercer grado de consanguinidad que lo requieran por razón de su edad o situación de discapacidad. Mientras que la obligación del empleador de dar una jornada laboral al semestre a sus trabajadores, pretende dar un espacio a los trabajadores para compartir con su familia. Todo lo anterior con el fin de brindar medidas de protección a la familia como núcleo esencial de la sociedad.
En relación con la jornada familiar semestral:
- Ésta aplica para que los trabajadores disfruten de dicho espacio con los miembros que de manera razonable y proporcional se consideren como parte de su familia y puede, por mera liberalidad del empleador, extenderse a personas adicionales que el empleador determine.
- No debe reprogramarse para aquellos trabajadores que no pudieron asistir por encontrarse incapacitados, de licencia o vacaciones el día en que ésta se llevó a cabo.
- No puede acumularse con jornadas familiares no disfrutadas por el Trabajador.
- El empleador puede establecer un horario laboral complementario para compensar el tiempo otorgado para la jornada familiar semestral, estando el empleador en la obligación de compensar las horas extra y recargos que se lleguen a dar con ocasión de dicho trabajo complementario.
- Los beneficios extralegales otorgados por mera liberalidad del empleador o acordados por medio de convenciones colectivas no eximen al empleador de cumplir con la obligación de dar una jornada familiar semestral a sus empleados.
- Debe darse una como mínimo por semestre, sin embargo, el empleador puede disponer de más de una jornada familiar por semestre para que distintos grupos de trabajadores puedan acceder a ellas en diferentes fechas.
- No puede realizarse en días de descanso del trabajador.
- Su incumplimiento puede acarrear la imposición de multas entre 1 y 5.000 SMLMV por parte del Ministerio de Trabajo dependiendo de la gravedad de la infracción.
Directorio de Servicios al Inversionista de ProColombia
PM Legal News – July 2026
External Circular 100-000020 of 2026
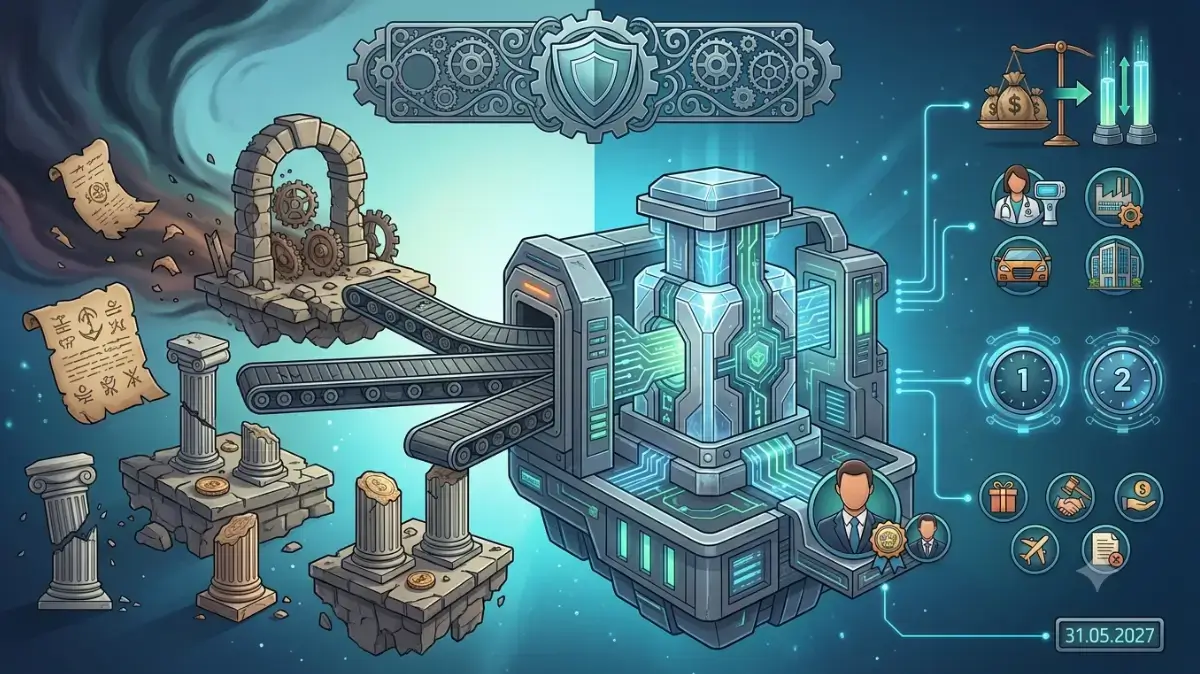
On July 2, 2026, the Superintendency of Corporations issued External Circular 100-000020, which adopts a new Basic Legal Circular and comprehensively amends the regulatory framework applicable to the prevention of:
- Money laundering (LA)
- Terrorism financing (FT)
- Financing of the proliferation of weapons of mass destruction (FP)
- Corruption and transnational bribery (C/ST)
Repeal of Previous Regulations
The new circular repeals and replaces the following External Circulars:
- 100-000016 of 2020 (SAGRILAFT – Chapter X)
- 100-000011 of 2021 (PTEE – Chapter XIII)
Important Changes
SAGRILAFT and PTEE are consolidated into a single instrument titled: “LA/FT/FP and C/ST Self-Regulation and Risk Management System,” contained in Chapter IX of the new Basic Legal Circular.
- The term “obligated company” is changed to “obligated entity.”
- The acronym FPADM (Financing of the Proliferation of Weapons of Mass Destruction) is simplified to FP.
- With regard to the financial thresholds that determine the system’s scope of application, the Current Legal Monthly Minimum Wage (SMLMV) will no longer be used as the reference unit; instead, Basic Value Units (UVB) are adopted.
- The Colombian Confederation of Chambers of Commerce (CONFECÁMARAS) is included as an obligated entity.
- Under the Minimum Measures Regime, several sectors that were not previously covered are also incorporated:
- The pharmaceutical sector (ISIC 2011 codes 2100, 3250, 4645)
- The manufacturing sector
- The mining and energy sector
- The vehicle trade sector (ISIC codes 4511, 4512, G4541), which is also subject to the full system when it exceeds the respective threshold
- Monitoring: Minimum frequency of once per year for high-risk counterparties. Minimum frequency of once every two years for medium- or low-risk counterparties.
- Regarding transparency and business ethics, mandatory policies must be established, such as those covering: the delivery and offering of gifts or benefits to third parties, political contributions, donations, travel and lodging expenses, and the filing and preservation of documents.
- The appointment of a deputy compliance officer is required; this individual must meet the same qualifications and requirements established for the principal compliance officer.
- Compliance officers must demonstrate and update their knowledge of ML/TF/FP and C/ST risk management at least once every three (3) years, in addition to demonstrating a minimum of one (1) year of professional experience in positions related to regulatory compliance in ML/TF/FP and C/ST risk management activities. Training is validated through formal education programs—specializations or master’s degrees—or through informal education programs, that is, “certificate programs provided they have a minimum duration of ninety (90) hours” with a direct and specific relationship to the subject matter.
Differences from the Previous Regulation
Previously: two parallel systems (SAGRILAFT – Chapter X / PTEE – Chapter XIII).
- Problem: duplication of obligations, bodies, and reporting requirements.
- Now: a comprehensive approach that manages all risks jointly.
Transition Period and Recommendations
- Regulated entities must make the required adjustments to the new system by May 31, 2027.
- During the transition period, the current systems will remain valid.
Peña Mancero Abogados offers support in the integration of systems and implementation of the necessary adjustments to ensure compliance with the new obligations within the established deadline.
Public Works for Taxes in Bogotá: An Opportunity to Turn Your Tax Burden into Tangible Impact
Companies seeking to maximize the value of their social investment and strengthen their relationships with communities now have an innovative alternative for fulfilling part of their tax obligations: the “Works for Taxes” (Obras por Impuestos) program.
“Works for Taxes” is an alternative mechanism through which companies can pay a portion of their taxes in Colombia by carrying out projects that help reduce socioeconomic disparities. This mechanism does not reduce companies’ tax burden, but it can generate specific benefits.
In Bogotá, the “Works for Taxes” program can facilitate the creation of partnerships between companies, local communities, and the District. Furthermore, it allows for a more efficient and transparent use of tax revenues, as these funds are channeled toward specific public works projects. In this way, companies’ tax contributions become more visible and tangible.
At our firm, we assist domestic and international companies in structuring, feasibility studies, negotiation, and execution of projects under this scheme, helping them manage the legal, regulatory, and contractual risks that arise throughout the process.
What Are “Works for Taxes”?
The “Works for Taxes” program is a mechanism that allows individuals and legal entities to allocate a portion of their taxes to the financing and implementation of projects that contribute to social development and the closing of socioeconomic gaps.
Although this mechanism does not reduce the tax burden, it does allow the funds that a company is required to pay to be channeled into specific projects that are visible to the beneficiary communities.
In Bogotá, this program has become particularly significant due to its ability to coordinate efforts among the private sector, communities, and district agencies to promote projects with high social impact.
Key Considerations for Companies
Companies interested in participating should keep in mind that:
- The projects are funded with private resources contributed by taxpayers.
- The taxpayer assumes full responsibility for implementation.
- Regulatory supervision is required.
- Cost overruns are not reimbursed.
- The project must address the District’s needs and interests.
- The taxpayer may enter into contracts under its own contracting regime.
These characteristics make adequate legal, tax, and contractual planning essential from the project’s initial stages.
How does the process work?
A company’s participation in the mechanism involves several stages:
- Identification of the project, whether it is an existing initiative or a proposal from the taxpayer.
- Project structuring, including the definition of scope, costs, risks, and timeline.
- Management of the feasibility study with the relevant district authority.
- Approval and allocation of the quota by the relevant authority.
- Formalization of the contract and project execution.
Each of these stages requires careful legal analysis to ensure compliance with regulatory requirements and minimize contingencies during implementation.
Two ways to participate
Trust (Fiducia) Option
Under this option, the company deposits a portion of the tax it was required to pay into a separate trust fund and receives a certificate that it may use at a later date.
Agreement (Convenio) Option
Under this program, the taxpayer enters into an agreement with a district government agency, carries out the project using their own funds, and receives, in return, District Territorial Renewal Certificates (TRTD), which they may later use to pay district taxes (property tax, vehicle tax, and ICA).
Current Opportunities in Bogotá
The District Secretariat for Social Integration (SDIS) currently has a portfolio of six projects spread across twenty neighborhoods in Bogotá. These projects focus on two main areas: providing social services to vulnerable populations and adapting infrastructure to be inclusive for people with disabilities.
These initiatives represent an opportunity for companies that want to make a measurable social impact while actively participating in the city’s development.
How can we help?
Our firm provides comprehensive advisory services to companies at every stage of Works-for-Taxes projects, including:
- Eligibility analysis and participation strategy.
- Legal and contractual structuring of the project.
- Regulatory due diligence.
- Negotiation of agreements and implementation contracts.
- Risk management and regulatory compliance.
- Support during project execution and supervision.
- Dispute resolution and claims handling.
The implementation of the open finance system in Colombia: transition towards an open data ecosystem
By Daniel Peña Valenzuela, Partner at Peña Mancero Abogados
Introduction
Decree 368 of 2026 introduced in Colombia the Mandatory Open Finance System, conceived as an institutional and technological transformation mechanism within the financial sector. This system constitutes the first step towards a broader model of data exchange, aimed at fostering innovation, competition, and financial inclusion. The main challenges lie in: (i) achieving a gradual implementation that ensures technical interoperability, (ii) safeguarding financial consumer protection, and (iii) preserving prudential stability, while building a trust-based ecosystem around data as a public resource.
1. Building the Open Finance System
The system is based on a hybrid model of mandatory and voluntary participation, accompanied by differentiated timelines according to the category of data. The implementation sequence foresees an initial six‑month phase for the definition of technical standards, followed by a twelve‑month period for the establishment of the Participants’ Directory and monitoring indicators. Effective access to information will be enforceable twelve months after the issuance of each standard, allowing entities to develop technical and operational capacities before assuming the obligations provided. The model will be mandatory for entities supervised by the Financial Superintendence, which must share information under the express authorization of clients. This scheme relies on a data governance system based on informed consent, an interoperable infrastructure supported by application programming interfaces, and periodic supervisory mechanisms. The creation of a Participants’ Directory and quarterly monitoring indicators seeks to ensure that the incorporation of new actors occurs without redesigning the system. Implementation also requires companies to strengthen their management of digital payments, insofar as open finance represents the next stage of sectoral development. The inclusion of the financial sector from the design phase reflects the intention to avoid regulatory lag and to adapt the system to the specificities of each subsector, such as cooperatives or insurers. In this context, any citizen will be able to authorize in seconds the use of their information to access better credit, insurance, or investment products, without physical procedures or additional certificates.
2. The Transition towards Open Data
Beyond open finance, the ultimate objective is to move towards an Open Data model involving heterogeneous sectors such as telecommunications, health, public services, and tax databases. Coordination among actors with different levels of digitalization and supervisory frameworks constitutes one of the main regulatory challenges. Building trust in information exchange becomes indispensable, especially regarding the progressive incorporation of non‑supervised providers such as fintech and insurtech, whose participation must avoid regulatory arbitrage. The balance between prudential stability and competitive openness requires a reinterpretation of regulation as a driver of innovation, beyond its traditional risk‑limiting function. The true purpose of the system demands the consolidation of an Open Data ecosystem integrating the financial, insurance, solidarity, and other sectors. This ecosystem must generate real value for citizens, facilitating access to credit, insurance, and investment products under more favorable and transparent conditions. In particular, the aim is to expand credit coverage, which remains low—between 35% and 40% of the adult population—highlighting the need to deepen financial inclusion in the country.
Conclusions
The Open Finance System represents a milestone in Colombian public policy, establishing the foundations for a model of information exchange that seeks to democratize access to financial services and promote innovation. Its gradual implementation and interoperable technical design are significant advances, but success will depend on institutional capacity to manage the transition towards Open Data. Trust‑building, intersectoral coordination, and consumer protection are necessary conditions for the system to fulfill its purpose of inclusion and competition. Ultimately, the challenge is not only regulatory or technological, but cultural: recognizing data as a public good and a driver of sustainable development. Information openness must be understood as a public policy tool which, far from being an end in itself, is oriented towards transforming the relationship between citizens and the financial system, expanding access opportunities and strengthening transparency in the digital economy.
Decree 0581 of 2026, Illegal Labor Outsourcing and Intermediation in Colombia
Newsletter Jun 2026
Decree 0545 of 2026, Issued May 29, 2026
“Whereby guidelines for the environmental planning of the Bogotá Savanna are established”
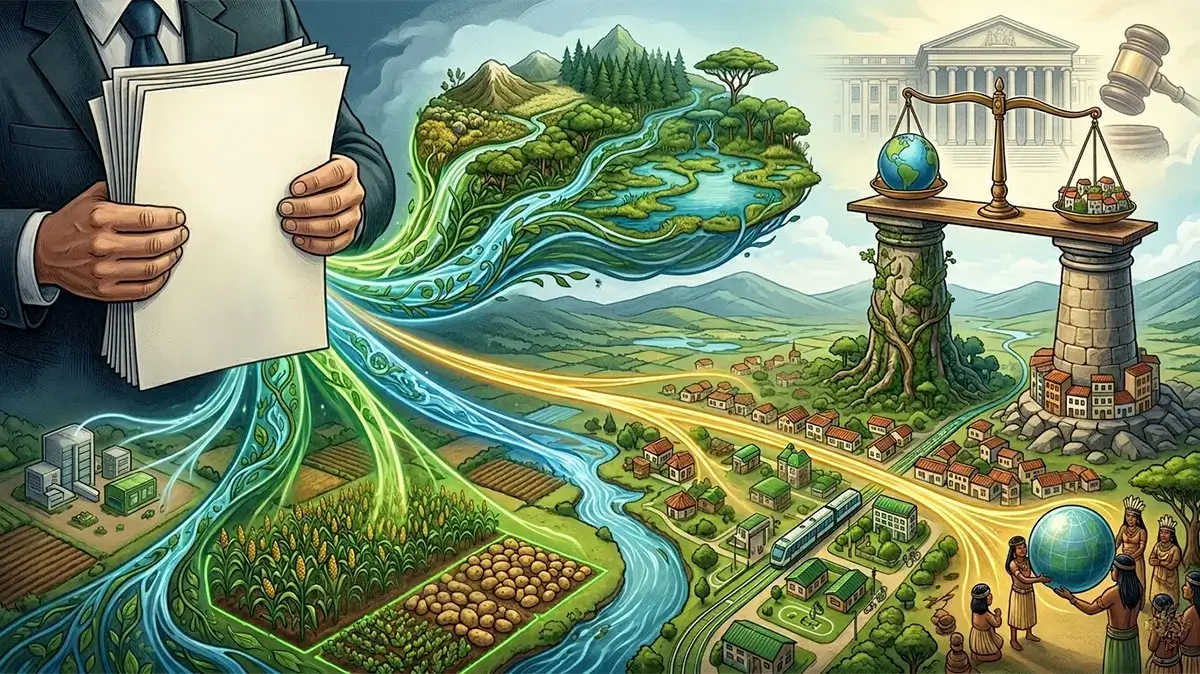
The National Government issued Decree 0545 of 2026 for the purpose of establishing guidelines for the environmental planning of the Bogotá Savanna, pursuant to the mandate set forth in Article 61 of Law 99 of 1993, which recognizes this region as an area of national ecological interest.
These guidelines constitute binding environmental planning criteria and rules of superior legal hierarchy that must be incorporated by territorial entities and considered by environmental authorities in the exercise of their respective powers.
The Decree applies to Bogotá D.C., the municipalities that comprise the Bogotá Savanna, and the authorities and entities responsible for territorial planning and land-use management.
The Bogotá Savanna encompasses 31 municipalities. The Decree applies in its entirety to: Cajicá, Chía, Cota, Funza, Gachancipá, Madrid, Mosquera, Nemocón, Sopó, Tabio, Tenjo, and Tocancipá.
It also applies partially to: Bogotá, Bojacá, Chipaque, Chocontá, Cogua, El Rosal, Cucunubá, Facatativá, Guasca, Guatavita, La Calera, Sesquilé, Sibaté, Soacha, Subachoque, Suesca, Tausa, Villapinzón, and Zipaquirá.
The Decree organizes its guidelines into five strategic components:
- Biodiversity conservation and climate change adaptation: promotes ecological connectivity, ecosystem restoration, and the protection of strategic areas.
- Integrated water resources management: strengthens the protection of aquifers, recharge areas, and surface and groundwater sources, prioritizing regional water security.
- Soil protection and conservation: establishes environmental criteria for urban expansion processes, preventing the degradation of land with high ecological and agricultural value.
- Sustainable infrastructure and green cities: requires new infrastructure projects to incorporate environmental criteria from the earliest stages of project planning, promoting sustainable mobility systems and nature-based solutions.
- Governance, information, and ancestral knowledge: incorporates mechanisms for interinstitutional coordination, open access to environmental information, and recognition of the traditional knowledge of Indigenous communities, particularly the Muisca people.
Key issues
- The Decree requires the updating of environmental mapping and watercourse buffer zones within specified timeframes.
- It promotes the ecological restoration of degraded areas and the protection of strategic ecosystems such as wetlands, Andean forests, and páramos.
- The Decree establishes a transition regime and clarifies that it does not alter vested legal rights or previously adopted planning instruments.
The environmental planning criteria must be incorporated into POTs and other planning instruments within twelve (12) months of the Decree’s effective date, beginning on May 29, 2026. During this period, priority will be given to environmental mapping, zoning, and the corresponding regulatory adjustments.
The Decree does not automatically modify projects that are covered by final administrative acts or environmental permits issued prior to its effective date, provided that such projects are carried out in accordance with the conditions established therein. However, these projects must assess related environmental risks and, where required by the competent authorities, adopt additional mitigation or compensation measures.
The municipalities identified in the Decree may face significant constraints on their autonomy to determine land use and guide their own development under the framework established by the Decree.
Property owners may face restrictions on land use and on the development of new urban projects within protected areas. Although ownership rights remain intact, owners may not freely develop, subdivide, construct on, exploit, or alter the use of their land when it is subject to environmental planning criteria. This is because the guidelines established by the Decree constitute binding criteria and rules for territorial and environmental planning and are considered rules of superior legal hierarchy within their respective spheres of competence.
The importance of protecting the Bogotá Savanna, its ecosystems, and its communities is beyond dispute. The legal issue, however, is whether the Decree maintains the constitutional balance between environmental protection of national significance and municipal autonomy.
The Constitution requires these two principles to coexist harmoniously. Therefore, the debate is not about the State’s authority to intervene, but rather whether certain provisions of the Decree exceed that authority and, in practice, displace decisions that the Constitution reserves to municipalities. This issue will likely be adjudicated by the courts, whose interpretation will ultimately define the boundaries between environmental powers and municipal autonomy.
Post-quantum digital signature and the reform of law 527 of 1999 in Colombia
By Daniel Peña Valenzuela
Introduction
Law 527 of 1999 marked a milestone in the regulation of electronic commerce in Colombia by recognizing the digital signature as a legal mechanism equivalent to the handwritten signature. This recognition consolidated trust in electronic transactions and granted evidentiary security to digital documents. The advent of quantum computing, however, poses an unprecedented challenge: the cryptographic algorithms underpinning digital signatures, such as RSA and ECC, may become vulnerable to the processing power of quantum computers. In this context, it is necessary to rethink the legal category of the digital signature and project regulatory reforms to ensure its validity in a post-quantum environment.
1. Digital signature under Law 527 of 1999
Law 527 establishes that the digital signature is an authentication mechanism based on public-key cryptography, guaranteeing the integrity and authenticity of electronic documents. The principle of technological neutrality allows any reliable method to be considered a digital signature, provided it meets security and functional equivalence standards. This principle must be reinterpreted in light of quantum risks, since legal validity depends on the technical robustness of the algorithms employed.
2. Quantum threat to digital signatures
Advances in quantum computing, particularly Shor’s algorithm, enable the factorization of large numbers and the resolution of discrete logarithm problems in polynomial time, directly undermining RSA and ECC. Likewise, Grover’s algorithm reduces the complexity of brute-force attacks on symmetric systems. These developments imply that current digital signatures may become vulnerable, weakening their evidentiary value in judicial and contractual processes.
3. Verifiable technical elements
The transition to a post-quantum environment requires the adoption of algorithms resistant to quantum attacks. The NIST (National Institute of Standards and Technology) selected between 2022 and 2024 algorithms such as CRYSTALS-Kyber for encryption and CRYSTALS-Dilithium for digital signatures. Similarly, ISO/IEC JTC 1 is working on international standards for post-quantum cryptography applicable to digital signatures. These verifiable technical elements form the basis upon which Colombian legislation must be reformed.
4. Need for reform of Law 527
The reform must explicitly recognize post-quantum algorithms as valid for digital signatures. It should also establish mechanisms for international interoperability with NIST and ISO standards, introduce the principle of technological resilience, and reinforce evidentiary guarantees to ensure that post-quantum digital signatures retain their functional equivalence with handwritten ones.
5. International comparison
In the European Union, the eIDAS 2.0 Regulation discusses the integration of quantum-resistant mechanisms. In the United States, NIST leads the standardization of post-quantum algorithms, directly impacting the validity of digital signatures. In Latin America, Colombia and Mexico have not yet explicitly incorporated the quantum threat into their legal frameworks, creating a regulatory gap and an opportunity for regional leadership.
Conclusions
The digital signature, as a legal category, faces a structural challenge in the quantum era. Reforming Law 527 is essential to recognize the post-quantum digital signature, adopt international standards, and guarantee the continuity of its functional equivalence. The post-quantum future does not eliminate the digital signature but requires its legal and technical transformation. Colombia must anticipate this transition to maintain legal certainty in electronic commerce and strengthen trust in digital transactions.
Gamification of Trading and Consumer Protection in Colombia: The Challenges of Using Foreign Platforms
By Daniel Peña Valenzuela, Partner Peña Mancero Abogados
Introduction
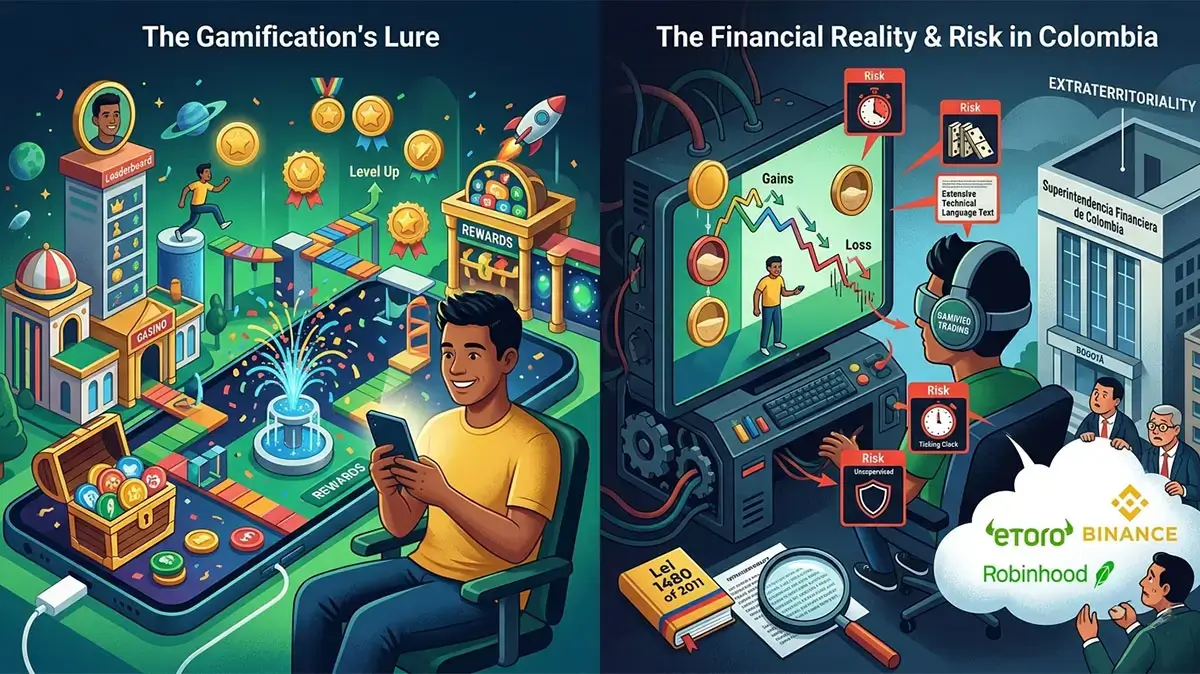
Gamification in trading has become a central strategy for digital platforms to attract and retain users. Through playful elements such as badges, rewards, leaderboards, and visual notifications, trading is transformed into a game-like experience. However, in Colombia, this practice raises serious consumer protection concerns, particularly when foreign platforms operate beyond the direct supervision of the Colombian Financial Superintendence.
This article examines the risks of gamified trading for Colombian consumers, highlights examples of international platforms such as Robinhood, eToro, and Binance, and proposes regulatory and cooperative mechanisms to mitigate digital manipulation in financial markets.
Dynamics of Gamification and Risks for Colombian Consumers
The logic of gamification in trading relies on behavioral stimuli designed to encourage frequent transactions. These stimuli, such as badges or visual rewards, create a sense of immediate achievement that can push users to repeat actions without properly assessing risks. A clear example is Robinhood in the United States, which was criticized for using digital confetti after trades, reinforcing emotional bias toward repeated trading.
Risks for Colombian consumers are significant. Gamification exploits behavioral biases such as loss aversion and the illusion of control, leading to impulsive decisions. Moreover, the extraterritoriality of platforms like eToro, based in Cyprus, or Binance, registered across multiple jurisdictions, makes direct oversight by the Colombian Financial Superintendence difficult. Finally, the information provided by these platforms often fails to meet the transparency standards required under Law 1480 of 2011, leaving consumers exposed.
Practical examples highlight these dynamics. Robinhood encourages high-frequency trading through simple interfaces and attractive visual cues. eToro promotes “copy trading,” where users replicate other investors’ strategies, potentially leading to uninformed decisions. Binance offers rewards and gamified token use, exposing consumers to volatile assets and increasing financial risk.
Conclusions
Gamified trading poses a challenge to consumer protection in Colombia. While it fosters financial inclusion, it also exposes users to manipulation and excessive risk. Needed measures include:
- International cooperation: bilateral and multilateral agreements to supervise foreign platforms.
- Warning protocols: clear digital messages about behavioral and financial risks.
- Financial education: programs teaching consumers to identify gamification techniques and their effects.
- Adaptive regulation: rules integrating consumer protection principles for digital and cross-border platforms.

Se modifican los lugares para la presentación de declaraciones tributarias en Cali
Ministerio de Agricultura y Desarrollo Rural reglamenta la metodología para el cálculo de la tasa y costo de servicios prestados por el ICA